What we’ve gained from the Affordable Care Act, 13 years later

Do you remember when some senior citizens had to ration their medications due to the fact their prescription drug expenses would triple each 12 months soon after they entered the Medicare protection gap identified as the “donut hole”? I do.

Do you recall when turning 19 intended getting kicked off your parents’ overall health insurance plan plan, regardless of your dwelling circumstance? I do.

Do you keep in mind when insurance policy firms could refuse to pay for preventive treatment options — vaccinations, mammograms, colonoscopies or a great number of other necessary products and services — for any motive, or maybe no purpose at all? I do.

Do you remember insurance plan corporations refusing coverage to pregnant females or many others with “preexisting conditions”? Or when they could cost you what they wished, for no matter what reason they wished, and you seriously had no selection but to accept that due to the fact there was no Patient’s Bill of Rights? I do.

But those times were being relegated to the dustbin of historical past on March 23, 2010, when President Obama signed the Economical Treatment Act (ACA) into regulation. Of class, as we mark the ACA’s 13th anniversary, it’s simple to ignore the political costs of that “miracle” laws. 

To start off with, it took a long time for Congress to draft and vote on the wellness treatment regulation. Then, the GOP built repealing the ACA its priority in the 2010 midterm elections. They demonized the law — labeled as “ObamaCare” — threw in a few of racist pet whistles and, with a nationwide disinformation campaign, rode a wave that received them back again manage of the Property of Associates and flipped 12 governor’s workplaces, together with Ohio, Pennsylvania, New Mexico and Michigan. This ushered in an era of obstructionism that described Congress for numerous decades.

In point, the GOP-managed Household voted a lot more than 50 times to repeal the ACA, disregarding the tens of hundreds of thousands of People in america who received health and fitness insurance coverage, and numerous others who have benefitted from the Patient’s Bill of Rights. Ironically, the one-minded devotion that won Republicans the Home greater part in 2010 would expense them that vast majority in 2018, adhering to a systematic schooling campaign that took the debate from abstract political philosophy to 1 centered on concrete truth.

A noted 13.6 million Individuals received insurance in 2021 by itself through that ACA marketplaces. Closing the prescription drug “donut hole” saved millions of Medicare recipients billions of bucks, and 2022 surveys by the Kaiser Family members Foundation and Morning Talk to uncovered that a bulk of Us citizens approve of the ACA. Staunch Republican opposition is shrinking.

It turns out that public feeling is even a lot more placing when you inquire people about distinct ACA provisions. For instance:

  • 90 per cent of People assist prohibiting wellbeing insurance policies companies from denying coverage for people today with preexisting problems
  • 89 per cent support demanding well being insurance coverage providers to deal with the cost for most preventive services
  • 88 {bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} aid prohibiting wellbeing insurance companies from denying protection to pregnant ladies
  • 87 per cent aid prohibiting wellbeing insurance coverage corporations from charging ill people today extra, and the very same share support providing states the alternative to increase Medicaid
  • 85 per cent assist providing economical enable to reduced- and average-cash flow People to buy coverage and
  • 78 per cent aid allowing younger grownups to keep on their parents’ insurance plan ideas until age 26.

Additional than 35 million Americans have well being insurance policies currently for the reason that of the ACA — guys, gals and young children who are benefiting from reduced charge and increased good quality wellbeing treatment coverage. They can thank the eyesight and bravery of leaders such as former Residence Speaker Nancy Pelosi (D-Calif.), former The vast majority Leader Steny Hoyer (D-Md.) and previous The vast majority Whip Jim Clyburn (D-S.C.), who socialized the concern and worked to safe the history-making votes in Congress.

These males and girls of conscience knew that “an ounce of avoidance is worthy of a pound of heal,” as the aged Ben Franklin declaring goes. They passed the most consequential overall health treatment legislation of my lifetime, proving that the age of heroes has not handed and that, in the words and phrases of Abraham Lincoln, our “government of the men and women, by the folks and for the people today shall not perish from the earth.”

Do you believe that in miracles? I do.

Antjuan Seawright is a Democratic political strategist, founder and CEO of Blueprint Strategy LLC, a CBS News political contributor, and a senior going to fellow at 3rd Way. Abide by him on Twitter @antjuansea.

Copyright 2023 Nexstar Media Inc. All rights reserved. This content may possibly not be published, broadcast, rewritten, or redistributed.

The Affordable Care Act has significantly reduced racial disparities in health care access, report says

The Affordable Care Act, passed in 2010 under former President Barack Obama, has expanded health insurance coverage across the U.S. and significantly reduced racial and ethnic disparities in access to health care, according to a new report by the Commonwealth Fund.

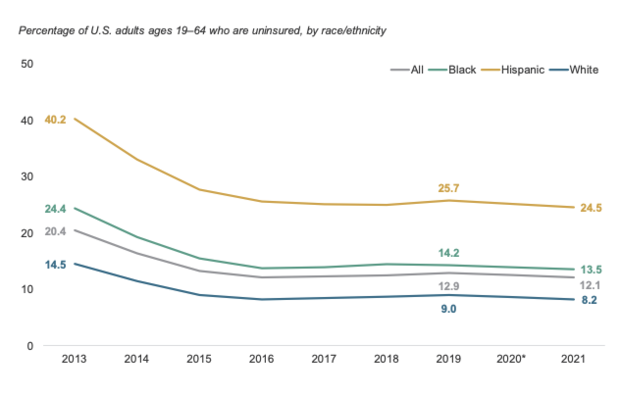
Percentage of U.S. adults ages 19–64 who are uninsured, by race/ethnicity
Coverage inequities between Black, Hispanic, and White adults have narrowed substantially since 2013. All groups reported improvements between 2019 and 2021.

The Commonwealth Fund


“Since its passage in 2010, the Affordable Care Act (ACA) has helped cut the U.S. uninsured rate nearly in half while significantly reducing racial and ethnic disparities in both insurance coverage and access to care — particularly in states that expanded their Medicaid programs,” reads the report.

Data shows that prior to the 2013 implementation of the Medicaid expansion — a provision of the ACA that made more families eligible for Medicaid coverage — 40.2{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the Hispanic population, 24.4{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the Black population, and 14.5{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the White population were uninsured in America. However, by 2021, those numbers dropped significantly to 24.5{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}, 13.5{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}, and 8.2{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}, respectively.

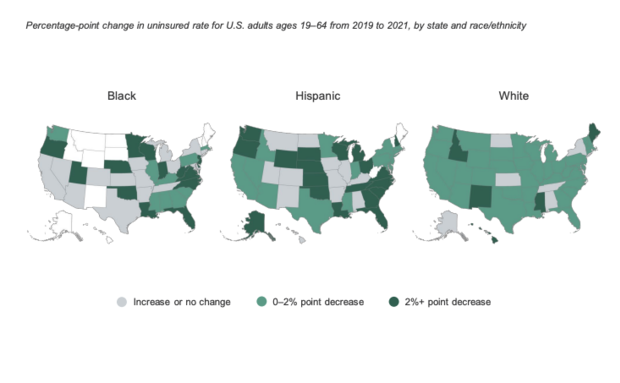
Percentage-point change in uninsured rate for U.S. adults ages 19–64 from 2019 to 2021, by state and race/ethnicity
Uninsured rates for Black and Hispanic adults improved considerably in several states between 2019 and 2021, while White adults experienced modest gains in most regions. 

The Commonwealth Fund


With more than 5 million people gaining coverage between 2020 and 2022 over the course of the pandemic, the overall uninsured rate in the U.S. dropped to just 8{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}, a historic low, according to the report.

The report highlights specific ACA successes, including improved coverage rates for Black, Hispanic and White adults.

“The coverage gap between Black and White adults dropped from 9.9 to 5.3 percentage points, while the gap between Hispanic and White adults dropped from 25.7 to 16.3 points,” according to the the study. 

Additionally, the report found that adult uninsured rates for Black, Hispanic, and White people all improved during the first two years of the pandemic across all states — whether they had expanded their Medicare coverage or not —  and that Black and Hispanic adults experienced larger gains in insurance coverage than their White counterparts between from 2019 to 2021.

A quirk in the Affordable Care Act is creating additional headaches.

Shock clinical costs are nothing at all new in the U.S., and they have come to be so commonplace in the 13 a long time since the landmark Cost-effective Treatment Act (ACA) became law that Congress lately passed laws aimed at banning the observe.

Occasionally a simple coding mishap can end result in a main headache for a client, as was the situation for Anthony, a 29-year-aged based mostly out of Norwalk, Conn.

When Anthony frequented his doctor for a regime yearly checkup — which his insurance policies system as a result of Cigna marketed as 100{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} included with no a copay — he finished up getting a monthly bill for $132.09.

This was simply because his doctor’s business coded the take a look at as an “office visit” instead of an “annual checkup or preventative care.” In an effort and hard work to distinct up the confusion, Anthony identified as both of those Cigna and his doctor’s office environment, and Cigna confident him that it was just detailed underneath the wrong code and would be protected if the doctor’s billing department corrected it.

“I submitted a grievance to Westmed, and they forwarded it to the billing section,” Anthony explained to Yahoo Finance. “They turned down my ask for a number of occasions. In accordance to them, the place of work staff members experienced the ultimate phrase on the billing code. I was able to converse to the office environment staff members specifically also, but I’m not absolutely sure who was responsible for selecting the billing code there.”

A quirk in the Affordable Care Act is creating additional headaches.

Healthcare Radiology Manipulator Ludovic Foy prepares a lady before her lung cancer screening on December 16, 2021. (Image by Pascal POCHARD-CASABIANCA/AFP)

The expertise, he added, has been “really disheartening” and time-consuming, particularly just after he achieved out to numerous offices to consider to remedy the challenge.

“Wasted a bunch of time, and, frankly, I obtained cheated,” Anthony said. “In the close, I received no explanation why they employed the mistaken code, and the invoice was despatched to collections. It’s heading to harm my credit score rating and in the U.S., that also suggests my potential to obtain a location to hire or even buy a home if I ever get the opportunity. It’s the sort of factor you get rid of slumber around.”

‘They consider shorter-term’

A loophole in the ACA — frequently identified as Obamacare — is element of the motive why this problem persists in the U.S.

Less than the ACA, insurers are needed to cover preventive solutions these kinds of as cancer screenings, immunizations, and effectively-girl visits without having price-sharing, which means that the particular person receiving the providers is not essential to pay anything at all.

A research published in 2021 in the journal Preventive Medication discovered that “in addition to premium charges intended to deal with preventive treatment, Us residents with employer-sponsored coverage were being nevertheless billed involving $75 million and $219 million in total for services that should to be totally free to them.”

In this March 23, 2010 photo, President Barack Obama signs the Affordable Care Act in the East Room of the White House in Washington. (AP Photo/J. Scott Applewhite, File)

In this March 23, 2010 picture, President Barack Obama indicators the Affordable Treatment Act in the East Room of the White Dwelling in Washington. (AP Picture/J. Scott Applewhite, File)

“The ACA specified these procedures about what should be included, but then how that is essentially operationalized is remaining up to person insurers — what method codes are included under the umbrella of every of those products and services in same or spirit, who qualifies, how normally they can get them is up to each individual insurer,” Paul Shafer, assistant professor of wellbeing, legislation coverage, and administration at Boston College School of Public Overall health, advised Yahoo Finance.

In addition, last September, Decide Reed O’Connor — who formerly ruled that the ACA was unconstitutional, a final decision that was later overturned by the Supreme Courtroom — issued a ruling that it was also unconstitutional for the ACA to demand insurers to include preventive services without the need of copayments.

If that ruling had been to stand, at least 40{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of grown ups indicated in a new Early morning Seek the advice of study that they would not be keen to pay out for a the greater part of the preventive solutions lined by the ACA mandate.

Even though the primary purpose of preventive visits is to reduce more time-expression difficulties from arising down the line — thus getting rid of likely expenses — insurers never usually see it that way, particularly if a service provider lists a various code on a patient’s file.

“They think brief-time period — and I’m talking in specific about the publicly-traded providers,” Wendell Potter, president of the Center for Well being and Democracy and previous executive at Cigna and Humana, advised Yahoo Finance. “They’re the types who are dominant in this location. They know there is a excellent likelihood that a man or woman who’s enrolled in a Cigna strategy now may well in the next 50 percent of this 12 months be enrolled in a United strategy, or even up coming thirty day period could be enrolled in a United strategy or a Humana approach. Persons alter work opportunities, and when they adjust positions, that usually necessitates that they have to get the job done with a new carrier with a new community of health professionals. And all of that goes with that.”

Fundamentally, insurance policy corporations increase by having current market share from each and every other, and Potter and other business industry experts refer to this as “churn.”

Former CIGNA executive Wendell Potter moderates a forum on denied coverage by insurance companies March 10, 2010 in Washington, DC. (Photo by Alex Wong/Getty Images)

Former CIGNA executive Wendell Potter moderates a discussion board on denied coverage by coverage organizations March 10, 2010 in Washington, DC. (Picture by Alex Wong/Getty Photographs)

Therefore, Potter claimed, “they decide on to have a limited-expression target and don’t have the fascination truly in carrying out what is correct for anyone down the road mainly because they are just earning a guess that they very likely will not have that person enrolled for a lengthy period of time of time.”

The No Surprises Act, which became regulation in 2021, was intended to protect against sufferers from obtaining surprise medical charges. However, it also will come with one more loophole: The law safeguards people getting treatment from out-of-network suppliers and out-of-network crisis companies, but it isn’t going to utilize in instances where by the treatment is getting supplied by in-community vendors, irrespective of regardless of whether or not it ought to be free for the individual.

“Policymakers and employers and the media, to a large extent, are missing some essential parts of our well being care system that want a lot more scrutiny,” Potter claimed. “We are really focusing on a handful of precise parts exactly where individuals in unique are at a good downside. Increasingly, this is an area wherever we find people today are owning difficulties when there is a dispute or glitch in refusing to fork out a declare.”

Not-so-cost-free treatments

Simply because of these loopholes, sufferers normally come across on their own billed for routine techniques that commonly are totally covered by their health insurance plan.

Various people, who questioned to continue being unnamed due to privacy worries, shared with Yahoo Finance the types they ended up expected to signal in buy to be noticed for regime physicals and other preventive exams.

In a single of the types, an unique was instructed that if they talked over any new or long-term health care difficulties with their health practitioner, their insurance policies would be billed for each an place of work take a look at and a preventive wellbeing examination.

For another specific, their form indicated that if they discussed new acute disorders or a worsening chronic ailment, if a diagnostic take a look at was requested, or if a remedy modified, they would also be matter to two separate bills.

“There are a large amount of gray places but usually, individuals should not be billed,” Jenifer Bosco, a employees lawyer at the Countrywide Buyer Law Center, informed Yahoo Finance. “In the worst situation, some companies do engage in what’s referred to as upcoding where they will try out to invoice for factors or get reimbursed at a substantial amount for factors that actually need to be possibly preventive or should really be billed at a lower fee.”

For case in point, a preventive colonoscopy meant to monitor for most cancers is required to be protected at 100{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} by overall health coverage companies. Nevertheless, if a polyp is discovered and eliminated from the individual throughout that screening, that method turns into a “surgery” somewhat than a screening and is billed as such.

“It can make zero sense charging the expense of some thing or the value to the individual for a little something when they’re practically mid-method,” Bosco explained. “You can basically monthly bill two visits for the very same time, which I imagine intuitively just does not make a lot of sense to most folks. If you’re likely in for one particular check out, how can you be billed for two and also be losing that cost-free preventive pay a visit to at the very same time?”

According to the Preventive Medicine analyze, patients had been saddled with a complete of $12.8 million for preventive colorectal screenings in 2018, though wellness visits incurred expenses of up to $73.1 million.

“It feels a minor little bit like a bait and swap, and that’s not on the medical doctors,” Shafer said. “That’s just how we’ve established up the reimbursement guidelines and every little thing else. It is disheartening.”

—

Adriana Belmonte is a reporter and editor masking politics and wellbeing care plan for Yahoo Finance. You can comply with her on Twitter @adrianambells and access her at adriana@yahoofinance.com.

Click listed here for politics information connected to small business and revenue

Study the most recent economical and business information from Yahoo Finance

Eastern District of Kentucky | Medical Equipment Company Pays $7 Million to Resolve False Claims Act Allegations

LEXINGTON, Ky.— United Seating and Mobility, LLC, d/b/a Numotion (Numotion) has paid $7 million to resolve civil allegations that it made false statements in connection with claims for reimbursement it submitted to Kentucky Medicaid, two of Kentucky Medicaid’s Managed Care Organization contractors (MCOs), MO HealthNet (Missouri Medicaid), and D.C. Medicaid.

Numotion is a national supplier of durable medical equipment (DME), such as hospital beds, manual wheelchairs, power wheelchairs and accessories, and gait trainers.  The investigation involved DME that was “manually priced” by Medicaid payors in Kentucky, Missouri, and D.C.  Those Medicaid programs reimbursed manually priced DME based on the cost Numotion actually paid the manufacturer for the equipment.  Specifically, in Kentucky, reimbursement is based on “a manufacturer’s actual charges” billed to Numotion, or the “invoice price;” in Missouri, reimbursement is based on the “actual invoice of cost;” and in D.C., reimbursement is based on “original documentation reflecting all discounts.”

In the Settlement Agreement, the United States alleged that Numotion did not disclose all discounts Numotion received from, or the cost Numotion actually paid to, DME manufacturers when submitting claims for manually priced DME to Kentucky Medicaid, two Kentucky Medicaid MCOs (Aetna Better Health of Kentucky and WellCare of Kentucky), MO HealthNet, and D.C. Medicaid.  Numotion’s failure to disclose all discounts, or the actual cost paid, resulted in these Medicaid programs paying Numotion higher reimbursements than it was entitled to receive.  The United States contended that the conduct violated the False Claims Act, 31 U.S.C. § 3729(a)(1)(B), a federal law that prohibits knowingly making or using a false statement material to a false claim for reimbursement. 

As part of the settlement, Numotion also entered into a 5-year Corporate Integrity Agreement (CIA) with the U.S. Department of Health and Human Services Office of Inspector General.  The CIA requires, among other things, that Numotion implement a centralized risk assessment program, as part of its compliance program, and hire an Independent Review Organization to complete annual reviews of some of its Medicare and Medicaid claims.

“By hiding or failing to disclose discounts, to receive higher reimbursement from Medicaid programs across the country, Numotion prioritized its financial incentives, to the detriment of these Medicaid programs,” said Carlton S. Shier, IV, United States Attorney for the Eastern District of Kentucky.  “Whenever the valuable resources of government health care programs are improperly dissipated to those who are not entitled, it diminishes the ability of these programs to meet the needs of their beneficiaries.  We remain committed to doing our part to protect these programs from fraud, waste, and abuse and to preserve the taxpayer money that supports them.”

“When health care companies do not follow federal health care billing requirements, the integrity of those safety net programs can be undermined,” said Special Agent in Charge Tamala E. Miles of the U.S. Department of Health and Human Services Office of Inspector General.  “Working with our law enforcement partners, the dedicated work of OIG’s investigators and attorneys has again resulted in the recovery of taxpayer dollars and better protection against improper billing in the future.”

The settlement resolves a lawsuit originally brought by L. Richard Parkey, a former Numotion employee, under the qui tam, or whistleblower, provisions of the False Claims Act.  Under those provisions, a private party can file an action on behalf of the United States and receive a portion of any recovery. As part of this resolution, Parkey will receive approximately $1.05 million of the settlement amount.

This case was investigated by the U.S. Department of Health and Human Services, Office of Inspector General.  Assistant United States Attorney Jennifer A. Williams handled the matter for the United States.

The case is United States ex rel. L. Richard Parkey v. United Seating and Mobility, LLC d/b/a Numotion, Case No. 3:17-cv-53-GFVT.  The claims resolved by the settlement are allegations only, and there has been no determination of liability.


– END –

The Healthcare Freedom Act is a vital solution to runaway medical debt

As the pandemic lingers, contributing to rising inflation and looming economic recession, Americans from all walks of life may be concerned about their medical bills. 

The Healthcare Freedom Act, proposed by Rep. Chip Roy (R-Texas), seeks to help Americans regain control of their healthcare expenses by creating “health freedom accounts” similar to existing health savings accounts. Health savings accounts enable patients to save pretax dollars for future medical expenses, but are limited to only those with high-deductible health plans, and contain numerous restrictions on what types of healthcare spending may qualify. Roy’s bill would allow any American, regardless of their health insurance type, to become eligible for health freedom accounts, as well as expand the list of qualified medical expenses. 

As a physician, I call upon Congress to pass this legislation in order to provide patients greater autonomy over their healthcare. 

Health savings accounts were first established in 2003 as part of the Medicare Prescription Drug Improvement and Modernization Act and became more prevalent as more employers began offering high-deductible health plans over the past 20 years. Many patients with high deductible plans never meet their annual deductible, and thus are forced to rely on money from their health savings account to cover routine health expenses; for these individuals, any money spent on insurance premiums by themselves or their employer is wasted. To make matters worse, current regulations also prohibit the use of health savings accounts to pay for insurance premiums. These policies serve only to enrich insurance companies at the expense of patients and private employers.  


Black Friday and Cyber Monday deals from BestReviews:

The Healthcare Freedom Act is a vital solution to runaway medical debt

Currently, HSAs allow maximum family contributions of up to $7,300 per year to a tax-deductible account, which enables the contributions to be untaxed for that year. In addition, the money grows tax-free and may be withdrawn from the account untaxed. These tax-protective mechanisms are how HSAs came to be known by the coveted descriptor “triple tax-free.” In addition to allowing all Americans to obtain an HSA/HFA, the Healthcare Freedom Act would nearly double the yearly contribution limit to $12,000, and allow individuals 55 years or older to contribute an additional $5,000. These changes are necessary due to the rapid growth in healthcare costs which routinely outpaces the already-astronomical rate of inflation.  

The Healthcare Freedom Act would also expand the list of approved medical expenses to include insurance premiums, direct primary care physician subscriptions, and payment to Healthcare Sharing Ministries. The bill would enable money from HSAs to be spent on all of these, plus additional services that may not be covered by health insurance. For example, patients coming to dermatology clinics may use money from their HSA/HFA to pay for the removal of benign skin lesions or other procedures deemed as “cosmetic” by insurance companies.  From the physician side, it allows a wider range of practice possibilities that would enable doctors to practice more personalized medicine.  

If HFAs become commonplace, more patients will be able to obtain their medications through compounding and specialty pharmacies, cutting out middlemen and reducing costs. Indeed, physicians will be able to circumvent insurance headaches such as step therapy (requiring patients to fail certain categories of medications before insurance will cover alternative therapies) if patients can pay for their medications directly. As a dermatologist, I frequently use direct-to-consumer pharmacies to help patients obtain customized therapies for their skin. 

Healthcare freedom accounts would expand access to these services to patient populations who may not have the financial ability to pay for these treatments out-of-pocket. Employers may also like the added flexibility of HFA’s, as they would be able to offer the new health savings account as an employee benefit without being forced to subscribe to a group high-deductible health plan. 

The net effect of expanding the number of approved expenses would be increased patient and physician autonomy. From the patient side, the Healthcare Freedom Act allows them to spend their hard-earned savings in a way that most aligns with their values. 

As a physician, I look forward to serving patients based on the ideals of the Hippocratic Oath rather than following arbitrary guidelines created by insurance companies.  

Aamir Hussain is a resident physician practicing in Washington, DC. Rufus Sweeney, a medical student at the University of Wisconsin, assisted in the creation of this story.