Vaccines are now an election issue nationwide : Shots

Vaccines are now an election issue nationwide : Shots

Minnesota Republican Scott Jensen has appeared with various anti-vaccine activists. Their assist may have served him earn the condition principal for governor.

Ben Mulholland/Gray Tv/Pool/via AP


conceal caption

toggle caption

Ben Mulholland/Grey Television/Pool/by means of AP
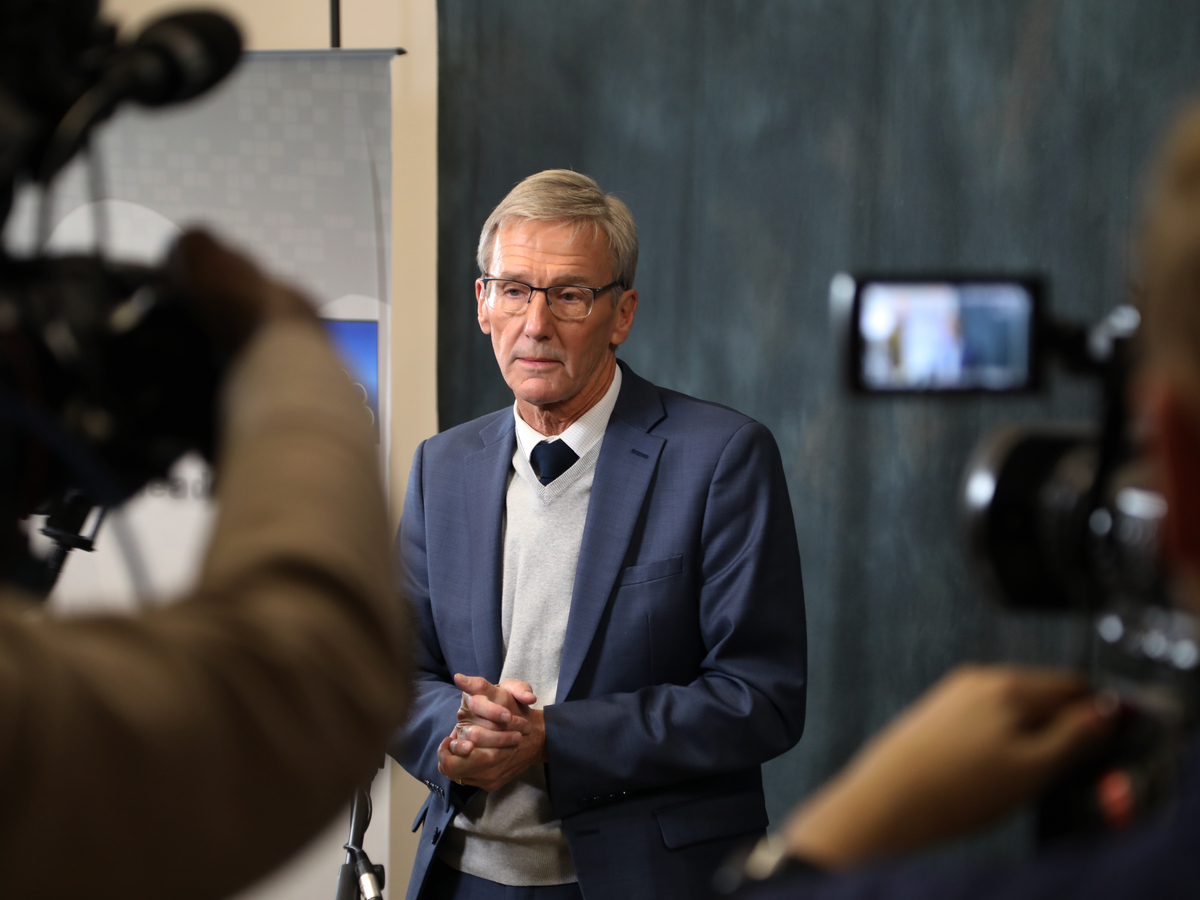

Minnesota Republican Scott Jensen has appeared with quite a few anti-vaccine activists. Their assistance may perhaps have served him earn the point out main for governor.

Ben Mulholland/Gray Television/Pool/by way of AP

In late Oct, the Republican applicant for governor of Minnesota posted a video clip he realized would be controversial.

“I’ve been named extreme, and perhaps this Fb video will provide fodder for extra individuals to contact me extreme,” the applicant, Scott Jensen, told his viewers. In the 20 minutes that followed, Jensen railed versus COVID vaccine mandates for youngsters, questioned the CDC’s vaccination timetable for other childhood immunizations, and elevated other obscure issues about COVID vaccines that have been credited with preserving hundreds of 1000’s of life.

“I consider in conditions of safety, the query is still out there,” he explained.

The 2022 midterm elections will be like no other: Hundreds of candidates on the ballot this 12 months challenge or deny the outcomes of the earlier election. But together with these phony narratives, candidates on the political right are also pushing conspiracies about vaccines.

Few candidates are as outspoken as Jensen, who has in the previous appeared together with many of the nation’s most notable anti-vaccine campaigners. But anti-vaccine rhetoric permeates the language of lots of Republican politicians. They are pleasing to a foundation who, emerging from the pandemic indignant above lockdowns and mask mandates, are progressively skeptical of vaccination.

Pro-vaccine advocates get worried that the increase of these candidates, together with an emboldened anti-vaccine motion, could spell trouble for community wellbeing in the many years to appear.

“I consider it truly is actually regrettable that an concern that has saved so lots of life has grow to be partisan and hyper-political,” claims Northe Saunders, the government director of the Harmless Communities coalition, a nationwide nonprofit dedicated to supporting professional-vaccine political candidates and guidelines.

On the ideal, anti-vaccine discuss delivers a political edge

Anti-vaccine proponents employed to exist in the two Republican and Democratic circles, but the pandemic noticed them shift definitively to the political proper. It was there that they observed allies battling lockdowns and masks. Republican politicians, specifically on the far right, have eagerly brought anti-vaccine forces into their tent. Anti-vaccine activists seem consistently at some well-known suitable-wing political functions, and some politicians have appeared on anti-vaccine exhibits in recent yrs.

Amongst them was Scott Jensen, a Minneapolis-region physician and condition senator, who pushed professional medical misinformation during the pandemic. Talking to anti-vaccine activist Del Bigtree in 2021, Jensen stated that hospitals distorted the range of COVID-19 fatalities. He has also questioned vaccine basic safety and pushed ivermectin — a drug that has been verified to be ineffective at treating COVID but proceeds to be promoted as an alternative treatment in anti-vaccine circles.

Jensen’s anti-vaccine views gave him an advantage when he entered the Republican most important for governor, claims Karen Ernst, the director of Voices for Vaccines, a Minnesota nonprofit that advocates for inoculation.

“Getting anti-vaccine absolutely aided Scott Jensen in the primaries,” Ernst suggests. Anti-vaccine activists are really organized and politically determined in the state, she claims. Jensen’s motivation to anti-vaccine suggestions aided get an edge in the crowded Republican subject.

But as the basic election approaches, it’s much less obvious irrespective of whether assistance from the anti-vaccine group can translate into political accomplishment. The huge bulk of Us citizens however think youngsters should be vaccinated, and Jensen’s opponent, Democrat Tim Walz, has received an endorsement from a significant Minnesota doctor’s group in section because he supports vaccination. Ernst claims Jensen might be hoping to soften his anti-vaccine image in the operate-up to the election. He bailed on a key anti-vaccine rally in Oct.

“He canceled at the last moment saying he experienced a marriage he experienced to attend,” she says, but he afterwards posted visuals on social media from a Minnesota Gophers soccer sport. “There was all types of hubbub about that.”

Threading the needle

But there are other techniques to enchantment to the anti-vaccine movement without having openly opposing vaccination. Anti-vaccine activists themselves have begun framing the troubles around vaccines as ones of bodily autonomy. They have fashioned a team recognized as “Stand for Wellbeing Independence,” which seeks to overturn vaccine mandates. The team, which was co-founded by a well known opponent of vaccines named Sayer Ji, promises to represent 50 percent-a-million Americans. It has advocated defunding the Entire world Wellness Group and urged a rollback of COVID vaccine mandates, but it stops small of spreading health-related misinformation on its have web-site. The group did not respond to NPR’s requests for an interview.

Among the politicians who have gained endorsement from the group is Florida Gov. Ron DeSantis. In a online video not too long ago posted to Twitter, DeSantis emphatically promised that he would not require kids to get COVID vaccines, while at the similar time, thoroughly preventing questions on vaccine protection.

“I mean you can get into some of the potential side-effects,” he claimed. “You will not even genuinely need to do that.”

DeSantis has also set up a doctor closely tied to the anti-vaccine motion as Florida’s surgeon standard.

Lisa Gwynn, the instant previous president of the Florida Chapter of the American Academy of Pediatrics, states DeSantis may not say instantly that he thinks vaccines are unsafe, but his language certainly speaks to the anti-vaccine movement.

DeSantis normally talks “like vaccines are terrible,” she says. She believes that the rhetoric is very carefully calibrated to energize the anti-vaccine things of the Republican base, without the need of showing to concern vaccines by themselves.

DeSantis has also taken ways to minimize COVID vaccine entry for underserved communities, Gwynn states. Florida does not offer you COVID vaccines to children below 5, and as a end result, reduced-revenue people seeking COVID vaccines at county overall health departments could see some of their children turned away. “Your 6-calendar year-aged can get a COVID shot, your 4-year-outdated are not able to get a COVID shot,” Gwynn says.

For now, considerably of the rhetoric is centered on COVID vaccines, but that could soon modify. Numerous states have found a surge in proposed legislation to weaken needs for childhood vaccines that shield from perilous conditions these kinds of as polio, mumps and measles. In 2018 there were roughly 81 expenses introduced nationwide that the professional-vaccine Risk-free team designates as anti-vaccine in 2022, they count much more than 1,500. “There is certainly absolutely a good deal much more anti-vaccine activity,” claims Saunders.

Saunders claims he believes that the anti-vaccine influence in politics is listed here to remain. “Unfortunately, I never consider the antivaxxers are at any time heading to go absent,” he claims.

What’s new for ACA health insurance open enrollment : Shots

What’s new for ACA health insurance open enrollment : Shots
Illustration of a group of people putting together a large scale puzzle on the floor. The image on the puzzle is the health care cross. Medications surround the people putting the puzzle together.

It’s fall again, meaning shorter days, cooler temperatures, and open enrollment for Affordable Care Act marketplace insurance — sign-ups begin this week for coverage that starts Jan. 1, 2023. Even though much of the ACA coverage stays the same from year to year, there have been a few changes you’ll want to take note of this fall, including those that might help you even if you don’t usually buy ACA insurance, but have been having trouble finding an affordable health plan through your employer.

In the past year, the Biden administration and Congress have taken steps — mainly related to premiums and subsidies — that will affect 2023 coverage, and could reduce your cost. Meanwhile, recent court decisions have triggered questions about what sorts of preventive care or abortion services each plan covers.

So, what’s new, and what should you know if you’re shopping for a health plan? Here are six things to keep in mind.

1. Sign up soon

Open enrollment for people who buy ACA health insurance via HealthCare.gov or one of the state exchanges begins Tuesday, Nov. 1 and, in most states, lasts through Jan. 15. To get coverage that begins Jan. 1, enrollment usually must occur by Dec. 15.

2. Your family might now qualify for a subsidy

One big change is that some families who were barred in past years from getting federal subsidies to help them purchase ACA coverage may now qualify.

A rule recently finalized by the Treasury Department aims to address what has long been termed the “family glitch.” The change expands the number of families with job-based insurance who can choose to forgo their coverage at work and qualify for subsidies to get an ACA plan instead. The White House estimates that this adjustment could help about 1 million people gain coverage or get more affordable insurance.

Before, employees could qualify for a subsidy for marketplace insurance only if the cost of their employer-based coverage was considered unaffordable based on a threshold set each year by the IRS. But that determination took into account only how much workers would pay for insurance for themselves. The cost of adding family members to the plan was not part of the calculation, and family coverage is often far more expensive than employee-only coverage. The families of employees who fall into the “glitch,” either go uninsured or pay more through their jobs for coverage than they might if they were able to get an ACA subsidy.

Now, the rules say eligibility for the subsidy must also consider the cost of family coverage.

“For the first time, a lot of families will have a real choice between an offer of employer-sponsored coverage and a marketplace plan with subsidies,” says Sabrina Corlette, a researcher and co-director at Georgetown University’s Center on Health Insurance Reforms.

Workers will now be able to get marketplace subsidies if their share of the premium for their job-based coverage exceeds 9.12{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of their expected 2023 income.

Thanks to the change in the rules, two calculations now will occur: the cost of the employee-only coverage as a percentage of the worker’s income and the cost of adding family members. In some cases, the worker may decide to remain on the employer plan because his or her payment toward coverage falls below the affordability threshold, but the family members will be able to get a subsidized ACA plan.

Previous legislative efforts to resolve the family glitch failed, and the Biden administration’s use of regulation to fix it is controversial. The move might ultimately be challenged in court. Still, the rules are in place for 2023, and experts, including Corlette, say families who could benefit should go ahead and enroll.

“It will take a while for all that to get resolved,” she says, adding that it unlikely that there would be any decision in time to affect policies for 2023.

An Urban Institute analysis published last year estimated that the net savings per family from this change in regulations might be about $400 per person, and the cost to the federal government for new subsidies could be $2.6 billion a year. Not every family would save money by making the change, so experts say people should weigh the benefits and potential costs.

3. Preventive care will still be covered everywhere without a copay, but abortion coverage will vary

Many people with insurance are happy when they go in for a cancer screening, or seek other preventive care, and find they don’t have to pay anything out-of-pocket. That comes from a provision in the ACA that bars cost sharing for a range of preventive services, including certain tests, vaccines, and drugs. But a September ruling by U.S. District Judge Reed O’Connor in Texas led to confusion about what might be included in that category next year. The judge declared unconstitutional one method the government uses to determine some of the preventive treatments that are covered without patient cost sharing.

Ultimately, that might mean patients will have to start paying a share of the cost of cancer screenings or pay part of the cost of drugs that prevent the transmission of HIV. The judge has yet to rule on how many people the case will affect. But, for now, the ruling applies only to the employers and individuals who brought the lawsuit. So, your no-cost screening mammogram or colonoscopy is still no-cost. Whatever the judge decides, his ruling is likely to be appealed, and no decision is expected before the start of the 2023 coverage year.

The other court decision that has raised questions is the Supreme Court ruling that overturned the constitutional right to an abortion. Even before that decision was announced in June, coverage of abortion services in insurance plans varied by plan and by state.

Now it’s even more complicated as more states move to ban or restrict abortion.

State insurance rules vary.

Twenty-six states restrict abortion coverage in ACA marketplace plans, while seven states require it as a benefit in both ACA plans and employer plans purchased from insurers, according to KFF. Those states that require abortion services to be covered are California, Illinois, Maine, Maryland, New York, Oregon and Washington.

If in doubt, employees and policyholders can check their insurance plan documents for information about covered benefits, including abortion services.

4. Premiums are going up, but that might not affect most people on ACA plans

Health insurers are raising premium rates for ACA plans and for employer coverage. But most people who get subsidies for their ACA health insurance won’t feel that pinch.

That’s because the subsidies are tied to the cost of the second-cheapest “silver” plan offered in an ACA marketplace. (Marketplace plans are offered in colored “tiers,” based on how much they potentially cost policyholders out-of-pocket.) As those baseline silver plans increase in cost, the subsidies also rise, offsetting all or most of the premium increases. Still, shop around, experts advise. Switching plans might prove cost-effective.

As for subsidies, passage this summer of the Inflation Reduction Act guaranteed that the enhanced subsidies that many Americans have received under legislation tied to the COVID-19 pandemic will remain in place.

People who earn up to 150{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the federal poverty level — so make up to $20,385 for an individual and $27,465 for a couple — can get an ACA plan with no monthly premium. Consumers who earn up to 400{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the federal poverty level — or $54,360 for an individual and $73,240 for a couple — get sliding-scale subsidies to help offset premium costs. And the premiums for ACA plans purchased by people who have higher incomes than that are also capped; according to the rules, they will need to pay no more than 8.5{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of their household income toward premiums.

For workers with job-based insurance, employers generally set the amount they must pay toward health coverage. Some employers may pass along their rising insurance costs by increasing the amounts taken out of paychecks to go toward premiums, setting higher deductibles or changing the health care benefits they offer. But anyone whose share of their job-based coverage is expected to exceed 9.12{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of their income in 2023 can check now to see whether they qualify for a subsidized ACA plan instead.

5. Debts owed to insurers or to the IRS won’t stop coverage

Thank COVID-19 for this one. Typically, people who get subsidies to buy ACA plans must prove to the government in their next tax filing that they received the correct subsidy, based on the income they actually received. If they failed to do that reconciliation with the IRS, policyholders would lose eligibility for the subsidy the next time they enrolled. But, because of ongoing COVID-related problems in processing at the IRS, those consumers will get another reprieve, continuing an effort set in place for tax year 2020 by the American Rescue Plan Act.

Also, insurers can no longer deny coverage to people or employers who owe past-due premiums for previous coverage, says Karen Pollitz, a senior fellow at KFF. This follows a reexamination of a wide variety of Medicare and ACA rules prompted by an April executive order from President Joe Biden.

“If people fell behind on their 2022 premiums, they nevertheless must be allowed to reenroll in 2023,” Pollitz says. “And when they make the first-month premium payment to activate coverage, the insurer must apply that payment to their January 2023 premium.”

6. Comparison shopping will likely be easier

Although ACA plans have always been required to cover a wide range of services and offer similar benefits, variation still existed in the amounts that patients paid for office visits and other out-of-pocket costs. Starting during this year’s open enrollment, new rules are taking effect that aim to make the comparison of plans easier. Under the rules, all ACA health insurers must offer a set of plans with specific, standardized benefits. The standard plans will, for example, have the same deductibles, copays, and other cost-sharing requirements. They will also offer more coverage before a patient has to start paying toward a deductible.

Some states, such as California, already required similar standardization, but the new rules apply nationally to health plans sold on the federal marketplace, HealthCare.gov. Any insurer who offers a non-standard plan on the marketplace must now offer the standardized plans as well.

Under a different set of rules, starting Jan. 1, all health insurers must make available cost-comparison tools online or over the phone that can help patients predict their costs for 500 “shoppable services,” such as repairs to a knee joint, a colonoscopy, a chest X-ray or childbirth services.

KHN (Kaiser Health News) is an editorially independent, national program of the Kaiser Family Foundation {KFF).