On 6 January 2023, the European Fee adopted a proposal to amend the transitional provisions of Regulation (EU) 2017/745 on health-related equipment (MDR) and Regulation (EU) 2017/746 on in vitro diagnostic healthcare equipment (IVDR).
The proposal aims to stop health care device shortages on the European Financial Area (EEA) market place. The proposed amendments introduce an extension to the transitional durations proven in the polices to deliver clinical device makers much more time to bring their gadgets into conformity with the specifications of the polices. In the circumstance of the MDR, the duration of the proposed extension is contingent on the possibility classification of devices.
The proposed amendments have been mentioned through a meeting of the Employment, Social Plan, Wellness and Customer Affairs Council held on 9 December 2022. Throughout the assembly, the frustrating majority of wellness ministers of the EU member states welcomed the proposed prolongation of the transitional intervals recognized in the MDR and the IVDR, and they underlined the urgency of delaying implementation of the laws. (For a lot more information on the assembly, refer to Cooley’s similar Productwise weblog write-up.)
The European Commission’s proposal to amend the transitional provisions proven in the MDR and the IVDR contains the subsequent things:
Extension of the transitional time period for bigger hazard(Course III and IIb implantable units) health-related units included by a CE certification of conformity issued before 26 May possibly 2021 in accordance with the Professional medical Gadgets Directive (MDD) or the Lively Implantable Clinical Units Directive (AIMDD) from 26 May 2024 to 31 December 2027.
Extension of the transitional interval for medium- and low-danger (other Course IIb units, Course IIa and sure Class I products) health-related gadgets accredited prior to 26 May perhaps 2021 in accordance with the MDD to 31 December 2028.
Introduction of a transitional period for Class III customized-made implantable gadgets until 26 May well 2026, provided that an software for a conformity evaluation is lodged with a notified entire body by the professional medical device maker by 26 May possibly 2024, and a agreement with the notified entire body is signed ahead of 26 September 2024.
Extension of the period of validity of certificates issued in accordance with the MDD and the AIMDD based on the product’s hazard course.
Removing of the “sell-off” deadline set up in Post 120.4 of the MDR and Short article 110.4 of the IVDR for healthcare equipment and in vitro diagnostics (IVDs), respectively, which usually means that healthcare devices and IVDs certified in accordance with the MDD, the AIMDD and the In Vitro Diagnostics Directive (IVDD) prior to the conclusion of the transitional period of time recognized in the MDR and the IVDR will be permitted to continue to be on the EEA market.
In accordance to the proposal, professional medical gadgets and IVDs would gain from the extended transitional periods if they fulfill sure conditions. Medical gadgets and IVDs ought to not present an unacceptable risk to individual and user wellbeing and basic safety. Furthermore, the application of the prolonged transitional durations would not address units that have gone through considerable variations in terms of their style and supposed reason. Companies also have to have commenced the process of transitioning their products to the MDR’s needs.
Motives driving proposed extension of transitional durations
Despite development in the implementation of the MDR and the IVDR, there have been considerable delays in the changeover of healthcare equipment and IVDs to the new procedures, as properly as worries in respecting the primary changeover deadlines delivered in the regulations. Restricted notified body availability and capacity, shortages in the source of raw supplies in the EU and deficiency of preparedness of manufacturers to carry their products into conformity with the rules are amongst the elements that have contributed to these delays and issues. To avert the risk of disruption to the provide and availability of professional medical products and IVDs on the EU market that could effect the protection of affected individual wellbeing, the European Commission proposed to allow for protected legacy gadgets to keep on being on the current market in the EEA soon after the stop of the at present relevant transitional period of time.
Subsequent methods
The proposal adopted by the European Fee will be regarded as for adoption by the European Parliament and the European Council by way of a co-selection process.
If adopted in its current variety, the proposed extension of the transitional provisions would have quite a few implications for the health-related gadget field. If you have any issues about the result of the extension of the MDR’s transitional interval, you should get to out to a member of Cooley’s life sciences regulatory staff.
World-wide mobility aid health-related units industry is envisioned to develop at a steady price in the course of the forecast period, 2024-2028. Mobility support healthcare gadgets assist the elderly and disabled persons in moving about. Quick technological breakthroughs in the growth of mobility support medical devices are the important variable responsible for its current market growth.
The demand for these units is expanding noticeably amongst the aged populace as they require treatment, safety and ease in shift and transfer, both of those in hospitals and homecare setups. Various initiatives are taken by the governments to enhance recognition about the use of mobility assist professional medical gadgets amongst the inhabitants and several health care enterprises. Other than, bettering health care infrastructure is also a big motive for the advancement in demand of these equipment.
In addition, assistive technologies help in decreasing challenges in performing working day-to-day things to do for aged and disabled populace. As a result, technological enhancements and new item launches by the key gamers functioning in the current market are predicted to build worthwhile progress alternatives above the following several many years.
The world wide mobility assist clinical devices sector is segmented into form, finish consumer, firm, and area. Based on style, wheelchair is predicted to hold the most dominant share during forecast period. Provision of wheelchair enhances the mobility and high quality of life and reduces common difficulties this kind of as tension sores as effectively as assists in improving upon digestion and respiration.
Regionally, North America is predicted to dominate the marketplace in the course of forecast period of time. This is attributed to the presence of very well-founded health care infrastructure alongside with the authorities initiatives with regards to the recognition of mobility help medical equipment. Other than, the rising adoption of highly developed technologies and growing investing for the growth of new items in the area, are the factors for the development in sector share of the location.
Big gamers functioning in the world-wide mobility help medical gadgets market include things like GF Overall health Items, Inc., Invacare Corporation, Pleasure Mobility Goods Corporation, Dawn Medical Constrained, OttoBock Health care GmbH, Permobil AB, Push Healthcare Ltd., Levo AG, Karman Healthcare Inc., and Meyra Wihelm Meyer GmbH & Co Ltd.
Report Scope:
World-wide Mobility Support Professional medical Equipment Market place, By Variety:
Wheelchairs
Handbook
Run
Going for walks Aids
Canes
Crutches
Walkers
Many others
Mobility Lifts
Ceiling Lifts
Hydraulic Lifts
Many others
Slings
Universal Slings
Bathing & Toileting Slings
Stand Up Slings
Tricycles
Manual
Powered
Mobility Scooters
3-wheel
4-wheel
Others
Global Mobility Aid Professional medical Gadgets Industry, By Close Person:
World wide Mobility Assist Medical Gadgets Current market, By Location:
Asia-Pacific
China
Japan
India
South Korea
Australia
Europe
Germany
France
United Kingdom
Italy
Spain
North America
United States
Mexico
Canada
South The usa
Brazil
Argentina
Colombia
Middle East & Africa
South Africa
Saudi Arabia
UAE
Crucial Matters Coated:
1. Product or service Overview
2. Analysis Methodology
3. Government Summary
4. Voice of Shopper
5. World wide Mobility Help Professional medical Devices Sector Outlook
6. Asia-Pacific Mobility Aid Professional medical Units Industry Outlook
7. Europe Mobility Support Health care Devices Industry Outlook
8. North America Mobility Assist Healthcare Units Current market Outlook
9. South The us Mobility Support Healthcare Products Market place Outlook
10. Center East and Africa Mobility Assist Health care Units Marketplace Outlook
About ResearchAndMarkets.com ResearchAndMarkets.com is the world’s top supply for worldwide current market study reports and market information. We give you with the hottest details on worldwide and regional marketplaces, vital industries, the top organizations, new merchandise and the most current tendencies.
U.S. and world wide health and fitness leaders say Beijing is not sharing plenty of facts about the unfold of Covid-19 in China, leaving the worldwide local community in the darkish about the scale and severity of the present-day wave of infection in the world’s most populous state.
The U.S. Centers for Sickness Manage and Prevention, in a statement Wednesday, claimed the lack of transparency from China could hold off the identification of new Covid variants that pose a danger to public health and fitness. China is sharing extremely handful of genomic sequences utilised to establish these kinds of variants, according to the CDC.
The CDC on Wednesday declared new testing necessities for airline passengers whose visits originate in China. All travellers, regardless of nationality or vaccination position, must get analyzed for Covid no more than two days in advance of their flight to the U.S. and current a unfavorable outcome to the airline before departure. The prerequisites go into impact on Jan. 5.
India, Italy, Japan and Taiwan have also imposed Covid take a look at requirements on airline travellers originating in China. The Chinese govt is battling a surge of infections immediately after easing its stringent zero-Covid coverage in the wake of social unrest before this calendar year.
Men and women get inhaled COVID-19 vaccine at the Center for Illness Manage and Prevention in Bijie, Guizhou province, China, December 29, 2022.
CFOTO | Future Publishing | Getty Visuals
A U.S. federal health official, in a get in touch with with reporters on Wednesday, said the Biden administration has extremely confined details on the amount of new Covid cases, hospitalizations and notably fatalities in China. Testing and casing reporting has also decreased in the place, which helps make the legitimate an infection price hard to decide, the official said.
China’s zero-Covid plan, which sought to crush outbreaks by critical steps, implies a substantial portion of the inhabitants does not have any immunity to the very transmissible omicron variants, the formal said. As a consequence, the Biden administration is forecasting that a large number of people today will be contaminated relatively promptly in China.
“What we’re involved about is a new variant that may emerge really in China,” said the official, who declined to be named as a condition of the push call. “With so many men and women in China remaining impacted in a quick period of time of time there is a opportunity, a chance that a new variant may perhaps arise.”
The latest genomic sequencing knowledge shared by overall health authorities in China suggests that Covid variants circulating in the country are similar to those recognized in the rest of the globe, according to a assertion this 7 days from GISAID, a general public databases primarily based in Germany.
In the past 180 times, China has sequenced and shared 412 Covid circumstances with GISAID, when compared to extra than 576,000 shared by the United States. Wellbeing authorities in China have shared fewer than 1{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of documented and sequenced Covid instances, whilst the U.S. has shared a lot more than 4{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} and the U.K. practically 12{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}.
The Earth Overall health Organization has also named on China to share far more data about what is transpiring on the ground as the virus distribute.
“WHO is quite concerned over the evolving scenario in China with increasing reviews of extreme condition,” claimed Dr. Tedros Adhanom Ghebreyesus, the head of the world overall health company, throughout a push briefing in Geneva final week.
CNBC Overall health & Science
Go through CNBC’s latest world wide health protection:
“In purchase to make a in depth possibility evaluation of the condition on the floor, WHO requires additional specific information on ailment severity, medical center admissions, and specifications for ICU support,” Tedros claimed.
The WHO mostly has anecdotal reports of unexpected emergency rooms and in some scenarios intensive treatment models filling up in China, in accordance to Dr. Mike Ryan, head of the world-wide health and fitness agency’s emergencies software.
“We don’t have comprehensive understanding of the effects,” Ryan mentioned of the Covid wave in China for the duration of the push meeting in Geneva very last week.
Dr. Maria van Kerkhove, the WHO’s Covid specialized guide, explained final week that omicron subvariants BA.5, BQ.1, BF.7 and BA.2.75 are all circulating in China. XBB has also been detected in China, which is a single of the most immune evasive variants yet.
The Institute for Wellness Metrics and Analysis, in a report published Dec. 15, claimed a significant wave of infection in China is unavoidable as Beijing relaxes its zero-Covid policy. There will be huge quantities of significant ailment in the elderly inhabitants and the loss of life toll will be appreciable, according to the report.
China faces a tough situation because its domestically created vaccines are not as helpful as Pfizer’s and Moderna’s mRNA shots. Vaccine protection amongst the elderly inhabitants in China also lags powering other nations.
“A single in 7 people on the world dwell in China and the acceleration of vaccination, the safety of the health and fitness technique all through this interval, is in the desire of seven out of 7 persons on this earth, Ryan claimed.
The U.S. has supplied China mRNA Covid vaccines and other assistance but Beijing has declined the give, the federal wellbeing formal said on Wednesday’s simply call.
This report features an extensive study of the current market landscape and future opportunities associated with the medical device contract research organizations market. The study also includes an in-depth analysis, highlighting the capabilities of various stakeholders engaged in this domain.
According to the World Health Organization (WHO), presently, around two million medical devices are available across the globe. Further, just over 35 medical devices received approval by the USFDA, every year. It is worth highlighting that, since 2020, the USFDA has approved around 105 medical devices.
Moreover, the medical devices are expected to capture more than 40{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the global medtech industry and this value is projected to grow at a steady pace over the coming years. In this context, the number of medical device focused clinical trials have increased at a considerable rate, over the past few years.
However, only a few players engaged in this domain claim to have the technical expertise to carry out in-house clinical research. This can be attributed to the high costs associated with acquiring the required infrastructure and capabilities to carry out research in this domain.
In addition, various regulatory guidelines render medical devices subject to rigorous quality assessments, thereby, making it difficult for firms with limited finances to undertake research initiatives. Specifically, post the onset of the COVID-19 pandemic, there has been a substantial increase in the demand for medical devices as they have the ability to enable early diagnosis, as well as provide non-invasive and effective treatments.
Given the surge in demand for medical devices in the recent past, coupled to the aforementioned constraints faced by developers, a large number of small, as well as well-established, players prefer to outsource a significant share of their respective clinical operations and regulatory affairs management to contract research organizations (CROs). Since 2010, over 75 CROs have been established in this domain.
Further, in order to support the growing demand, medical device CROs have been re-evaluating and bolstering their existing capabilities to offer a wide range of services to their clients. Integration of novel technologies and tools, such as cloud computing, risk monitoring tools, real-world evidence and advanced data analytics, is another key initiative being undertaken by several CROs to distinguish themselves from their competitors.
To enable expansion of their existing capabilities, more than 55 acquisitions and / or strategic alliances have been established by service providers in this market, since 2015. Considering the prevalent trends and projected opportunity associated with the overall medical devices market, we believe that the medical devices CROs market is likely to witness consistent grow, till 2035.
The report features detailed transcripts of interviews held with the following stakeholders:
Lajos Sarosi (Chief Executive Officer and Co-founder, HungaroTrial)
Lee King (Senior Vice President, Business Development and Marketing)
Christopher Rupp (Vice President of Global Marketing and Commercial Operations, NAMSA)
Claus Hemiker (Head, Business Development)
Christian Wolflehner (General Manager, CW Research & Management)
Troy W. Mccall (Chief Commercial Officer, CROMSOURCE)
Nazish Urooj (Senior manager, Medical & Clinical Operations, Metrics Research)
C. Omprakash (Technical Director and Partner, Vyomus Consulting)
Tania Persson (Director of Business Development, A+ Science)
Alexa Foltin-Mertgen (Business Development Manager, AtoZ-CRO)
All actual figures have been sourced and analyzed from publicly available information forums and primary research discussions. Financial figures mentioned in this report are in USD, unless otherwise specified.
Key Questions Answered
Who are the key players engaged in offering contract research services for medical devices?
Which regions represent the key contract research hubs for medical devices?
What are the key regulatory guidelines, related to medical devices that have been established across various geographies?
What are the key value drivers of the merger and acquisition activity observed within this domain?
What percentage of the medical devices research operations are presently outsourced?
What are the likely future trends in contract research services market for medical devices?
How is the current and future opportunity likely to be distributed across key market segments?
What is the total cost of ownership required to set up a medical device contract research organization?
Key Topics Covered:
1. PREFACE
2. EXECUTIVE SUMMARY
3. INTRODUCTION 3.1. Chapter Overview 3.2. Overview of Medical Devices 3.2.1. Historical Evolution of Medical Devices 3.2.2. Classification of Medical Devices 3.3. Overview of Contract Research Organizations (CROs) 3.3.1. Evolution of CROs 3.4. Role of CROs in the Medical Device Industry 3.5. Types of Medical Device CROs 3.6. Types of Services Offered by CROs 3.7. Advantages of Outsourcing Operations to CROs 3.8. Risks and Challenges Associated with Outsourcing 3.9. Key Considerations While Selecting a Suitable CRO Partner
4. MARKET LANDSCAPE 4.1. Chapter Overview 4.2. Medical Device CROs: Clinical Service Providers 4.2.1. Analysis by Year of Establishment 4.2.2. Analysis by Company Size 4.2.3. Analysis by Location of Headquarters 4.2.4. Analysis by Company Size and Location of Headquarters 4.2.5. Analysis by Area of Specialization 4.2.6. Analysis by Device Class 4.2.7. Analysis by Type of Clinical Operation Service Offered 4.2.8. Analysis by Type of Regulatory Affairs-related Service Offered 4.2.9. Analysis by Type of Additional Service Offered 4.2.10. Analysis by Medical Device Regulatory Compliance Authority 4.3. Medical Device CROs: Preclinical Service Providers 4.3.1. Analysis by Year of Establishment 4.3.2. Analysis by Company Size 4.3.3. Analysis by Location of Headquarters 4.3.4. Analysis by Company Size and Location of Headquarters 4.3.5. Analysis by Type of Preclinical Service Offered 4.4. Medical Device CROs: Standalone Service Providers 4.4.1. Analysis by Year of Establishment 4.4.2. Analysis by Company Size 4.4.3. Analysis by Location of Headquarters 4.4.4. Analysis by Company Size and Location of Headquarters
5. REGULATORY AND REIMBURSEMENT LANDSCAPE FOR MEDICAL DEVICES 5.1. Chapter Overview 5.2. General Regulatory and Reimbursement Guidelines for Medical Devices 5.3. Regulatory and Reimbursement Landscape in North America 5.4. Regulatory and Reimbursement Landscape in Europe 5.5. Regulatory and Reimbursement Landscape in Asia-Pacific and Rest of the World 5.6. Comparison of Regional Regulatory Control 5.7. Concluding Remarks
6. COMPANY PROFILES 6.1. Chapter Overview 6.2. Avania (Formerly known as Factory CRO) 6.2.1. Company Overview 6.2.2. Service Portfolio 6.2.3. Recent Developments and Future Outlook 6.3. Charles River Laboratories 6.3.1. Company Overview 6.3.2. Service Portfolio 6.3.3. Recent Developments and Future Outlook 6.4. CROMSOURCE 6.4.1. Company Overview 6.4.2. Service Portfolio 6.4.3. Recent Developments and Future Outlook 6.5. CSSi LifeSciences 6.5.1. Company Overview 6.5.2. Service Portfolio 6.5.3. Recent Developments and Future Outlook 6.6. Eurofins Medical Device Testing 6.6.1. Company Overview 6.6.2. Service Portfolio 6.6.3. Recent Developments and Future Outlook 6.7. IQVIA 6.7.1. Company Overview 6.7.2. Service Portfolio 6.7.3. Recent Developments and Future Outlook 6.8. Medpace 6.8.1. Company Overview 6.8.2. Service Portfolio 6.8.3. Recent Developments and Future Outlook 6.9. NAMSA 6.9.1. Company Overview 6.9.2. Service Portfolio 6.9.3. Recent Developments and Future Outlook 6.10. Qserve Group 6.10.1. Company Overview 6.10.2. Service Portfolio 6.10.3. Recent Developments and Future Outlook 6.11. WuXi AppTec 6.11.1. Company Overview 6.11.2. Service Portfolio 6.11.3. Recent Developments and Future Outlook
7. MEDICAL DEVICE DEVELOPER AND CRO RELATIONSHIPS: KEY VALUE DRIVERS AND PERFORMANCE INDICATORS 7.1. Chapter Overview 7.2. Definition and Importance of Key Performance Indicators (KPIs) 7.3. Key Considerations for Selection of KPIs 7.4. Types of KPIs 7.5. Comparison of Key Performance Indicators 7.6. Concluding Remarks
8. COMPETITIVE BENCHMARKING 8.1. Chapter Overview 8.2. Assumptions and Methodology 8.3. Competitive Benchmarking by Region 8.4. Concluding Remarks
9. BRAND POSITIONING OF KEY INDUSTRY PLAYERS 9.1. Chapter Overview 9.2. Scope and Methodology 9.3. Brand Positioning Matrix: Labcorp 9.4. Brand Positioning Matrix: IQVIA 9.5. Brand Positioning Matrix: Syneos Health 9.6. Brand Positioning Matrix: PPD 9.7. Brand Positioning Matrix: ICON 9.8. Brand Positioning Matrix: Charles River Laboratories 9.9. Brand Positioning Matrix: WuXi AppTec 9.10. Brand Positioning Matrix: Medpace
10. CLINICAL TRIAL ANALYSIS 10.1. Chapter Overview 10.2. Scope and Methodology 10.3. Medical Devices: Clinical Trial Analysis 10.4. Medical Devices: Analysis by Enrolled Patient Population
11. MERGERS AND ACQUISITIONS 11.1. Chapter Overview 11.2. Merger and Acquisition Models 11.3. Medical Device CROs: Mergers and Acquisitions
12. TOTAL COST OF OWNERSHIP IN MEDICAL DEVICES CONTRACT RESEARCH ORGANIZATION 12.1. Chapter Overview 12.2. Assumptions and Methodology 12.3. Expenditures Incurred by a Medical Device Contract Research Organization 12.4. Total Cost of Ownership of Medical Devices Contract Research Organizations, 2022-2042 12.5. Total Cost of Ownership of Medical Devices Contract Research Organizations: Analysis by CAPEX and OPEX Costs, 2022 and 2042 12.6. Concluding Remarks
13. SURVEY INSIGHTS 13.1. Chapter Overview 13.2. Designation of Respondents 13.3. Types of Services Offered 13.4. Target Therapeutic Area 13.5. Average Number of Annual Projects 13.6. Market Opportunity
14. MARKET SIZING AND OPPORTUNITY ANALYSIS
15. SWOT ANALYSIS
16. FUTURE TRENDS AND OPPORTUNITIES
17. INTERVIEW TRANSCRIPTS
18. APPENDIX 1: TABULATED DATA
19. APPENDIX 2: LIST OF COMPANIES AND ORGANIZATIONS
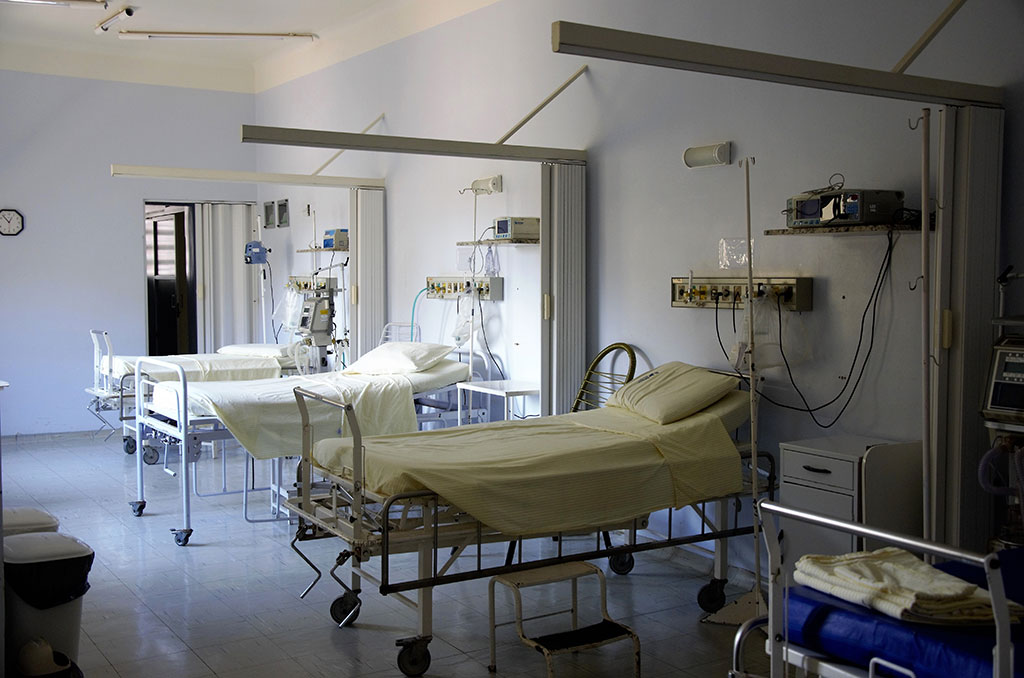
Image: The global refurbished medical equipment market revenue is expected to surpass USD 29 billion by 2027 (Photo courtesy of Pexels)
Purchasing a new piece of medical equipment comes with many upfront costs. And in a constantly changing industry, medical equipment can rapidly become outdated. Refurbishment is the systematic process of making used equipment equal to or better than new. Refurbishment is rebuilding or updating used equipment with new materials, components or parts to restore their original (or better) working condition and appearance. Refurbishment typically costs about half as much as buying a new one and can bring a machine back to a new-like condition. Refurbished equipment can help to avoid high upfront costs and being forced to use something that will quickly become obsolete. Refurbished medical equipment provides flexibility and also saves money by extending their lifespan to realize maximum return on investment. As a result, the global refurbished medical equipment market is projected to grow at a CAGR of 11.76{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} from USD 15.23 billion in 2021 to USD 29.68 billion by 2027, driven by increasing demand for medical equipment in the developing countries, high capital and procurement costs of new medical equipment, and growing preference for eco-friendly products. These are the latest findings of Arizton Advisory & Intelligence (Chicago, IL, USA), a market research firm.
Nearly one-third of the medical equipment industry in the developing countries is part of the refurbished medical equipment market. The dearth of access to medical equipment in the developing countries has attracted global interest in the refurbished medical equipment market for disease diagnosis. Healthcare systems in the low-and middle-income countries often have limited access to medical equipment for routine use. Implementing medical equipment refurbishment in a developing country provides employment, increases the knowledge of medical technology among the people, and thus, provides a sustainable supply of skilled personnel for the healthcare industry.
Medical equipment typically consists of complex machines that are expensive to purchase and operate and require significant maintenance. Small & medium-sized hospitals often cannot afford to buy new high-end equipment. Smaller clinics and local medical centers may not be inclined to spend their resources on purchasing limited new equipment that can easily deplete their entire annual budget. These facilities prefer refurbished equipment of reputed brands that will cost less but perform well for a few years without complaints. Purchasing refurbished medical equipment allows healthcare providers to maximize their budget while providing quality treatment options to each patient. By investing in refurbished equipment, hospitals and clinics can free up much-needed funds for other uses, such as staff, disposables, and medicines, further contributing to the growth of the refurbished medical equipment market. Additionally, refurbished medical equipment eliminates the annoying problems faced in using a worn-down machine and avoids the learning curve associated with new equipment.
Medical equipment inventory is an accepted cost of doing business for manufacturers and is often the most significant cost category. Since medical equipment is typically a high-value product, any efficiencies or cost reductions can quickly contribute to the bottom line. Older equipment does not last forever, and this equipment eventually will need to be replaced and refurbished. Many facilities are now eager to replace their older systems with the resolution of global supply chain problems. This will contribute to the rising sales of refurbished medical devices, aided by a large inventory of used medical equipment.
Refurbished medical equipment also offers environmental benefits. By extending the useful life of medical equipment from 5-7 to 10-14 years or even more, refurbishment is a form of reuse and waste prevention, contributing to an environmental economy. Refurbishment saves energy, and the materials are used to produce new equipment. Refurbishing medical equipment and extending its service life maximizes the return on the initial investment of energy and materials. Approximately 90{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the material for a system undergoing refurbishment can be reused; only 10{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the material must be recycled, which is done using environmentally friendly processes. In addition to important environmental benefits, refurbishing provides sustainable economic benefits by creating business and employment in the refurbished medical equipment market. Even existing equipment owners may consider refurbishing their machines rather than disposing off old ones and buying new ones if their users are comfortable using the specific model. A refurbished asset can be re-capitalized on a depreciation schedule at half the value of new equipment.
Based on product type, the medical imaging segment dominated the refurbished medical equipment market in 2021 with the highest share of 25.58{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}. The use of medical diagnostic imaging equipment can resolve between 70-80{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of diagnostic problems, but nearly 2/3 of the world’s population has no access to diagnostic radiology. Refurbished X-ray machines, ultrasound systems, MRI machines, CT scanners, and nuclear medicine systems (PET, SPECT, and PET/CT) allow healthcare facilities to provide patients with life-saving medical diagnostic imaging services. The medical imaging equipment segment is expected to record the highest incremental growth of USD 3.10 billion, while the IVD & laboratories equipment segment is expected to register the highest CAGR of 13.14{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} over the forecast period.
Based on application, the diagnosis & monitoring segment dominated the refurbished medical equipment market in 2021 with a share of 69.46{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}, followed by the treatment & surgical interventions segment. Medical equipment is extensively utilized for patients’ diagnosis and treatment. Diagnostic and monitoring applications comprise Cardiology, Urology, Neurology, Orthopedics, Physiology, Emergency Medicine, Oncology, Obstetrics/Gynecology (OB/GYN), and others. The diagnosis & monitoring segment is expected to register the highest incremental growth of USD 9.73 billion, while the treatment & surgical interventions segment is expected to register the highest CAGR of 12.40{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} over the forecast period.
Based on end-user, the hospital segment dominated the refurbished medical equipment market in 2021 with the largest share of 37.97{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f}. Hospitals utilize more medical equipment than any other healthcare setting. Diagnostics are the primary screening method in hospitals, which are the first point of contact for any infection and disease. The rising number of people with various infectious diseases compels physicians in hospitals to use diagnostic imaging equipment, thereby increasing their demand. The hospital segment is expected to register the highest incremental growth of USD 5.24 billion, while the clinical & research laboratories segment is expected to record the highest CAGR of 12.18{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} over the forecast period.
Geographically, North America and Europe are the matured markets for refurbished medical equipment. In 2021, North America dominated the global refurbished medical equipment market with a share of 28.24{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} and revenues of USD 4.30 billion, due to its aging population, prevalence of chronic diseases, growing healthcare expenditure, need for advanced imaging techniques, presence of well-established players, and a significant shift towards digital medical equipment in the region. Further, the US accounted for a share of 91.21{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} of the North American refurbished medical equipment market, led by an increasing diseased population, growing access to insurance, and faster adoption of advanced healthcare instruments for treatments in the country. Following North America, the refurbished medical equipment market was dominated by Europe, APAC, Latin America, and the Middle East & Africa. The APAC market for refurbished medical equipment is expected to register the highest CAGR of 14.45{bf0515afdcaddba073662ceb89fbb62b6b1bf123143c0e06b788e1946e8c353f} and the highest incremental growth of USD 4.84 billion over the forecast period, driven by constant public and private funding, advancements in diagnostic imaging models, and growing medical awareness.
The implementation of Regulation (EU) 2017/745 on medical devices (MDR) was discussed on the second day of the meeting of the Employment, Social Policy, Health and Consumer Affairs Council (EPSCO) on 9 December 2022. The European Commission proposes to extend the transition period currently foreseen in the MDR for devices certified in accordance with the Medical Device Directive (MDD) and the Active Implantable Medical Device Directive (AIMDD) through legislative amendment of the transitional provisions of the MDR. The extension of the transition period would be in the form of a staggered approach based on the risk classification of devices.
The transition period foreseen in the MDR provides that the deadline for recertification of medical devices in accordance with the regulation is 26 May 2024. A broad range of stakeholders, including the medtech industry, consider this timeline to be unattainable and have called on the European Commission to extend the recertification deadline. This extension would be based on the risk classification of devices and would mean that devices certified in accordance with the MDD and the AIMDD will remain on the market in the European Economic Area (EEA) after the end of the currently applicable transition period.
The European Commission proposes the following targeted legislative amendments:
Extension of the transitional provisions foreseen in the MDR based on the risk class of each device.
26 May 2027 for high-risk (Class III and Class IIb) medical devices
26 May 2028 for medium- and low-risk (Class IIa and Class I) medical devices
Elimination of the sell-off date of 26 May 2025 for medical devices that are already available on the EEA market to prevent safe medical devices from being removed from the market.
EU Commissioner for Health and Food Safety Stella Kyriakides noted that the proposed amendments would apply solely to medical devices that are safe for patients.
Following discussion with the health ministers of the EU member states, Kyriakides acknowledged the need for interim measures in relation to CE certificates of conformity previously issued for medical devices that have expired or will expire soon.
Shortly after the EPSCO meeting concluded, the European Commission published a position paper prepared by the Medical Device Coordination Group. The purpose of the position paper is to ensure a uniform approach to the application of market surveillance measures to bridge the gap between the expiration of certificates and the issuance of new certificates. The position paper provides guidance on how competent authorities should apply Article 97 MDR to devices that do not comply with the MDR due to expiration of their CE certificates of conformity issued in accordance with the MDD and the AIMDD before being certified under the MDR.
In addition to the proposed legislative amendments, the European Commission intends to undertake a comprehensive evaluation of the MDR by May 2027. The purpose of the evaluation is to identify structural problems with the MDR, as well as potential medium- and long-term solutions to these concerns. Moreover, the European Commission intends to fund actions to support the implementation of the MDR under the EU4Health programme starting in early 2023.
If you have any questions about the effect of the extension of the MDR transition period, please reach out to a member of your Cooley life sciences regulatory team.